Blog · Rewarding Heroes
Healthcare professionals: a home buying guide for Phoenix Metro
A step-by-step buying guide built for doctors, nurses, and other healthcare professionals in and around Phoenix: how the process works, which financing is worth verifying and which assumptions to drop, how to fit a search around shifts and contracts, and what the Rewarding Heroes program is and is not. No invented savings, no occupation-based assumptions, just the process done clearly.
 By Andrew Texidor Realtor · Founder, Clearly Sold · AI Certified Agent™ Updated October 30, 2026
The direct answer
Buying a home in Phoenix Metro as a healthcare professional is the same disciplined process as any other purchase, with three extra layers: verifying which financing products actually apply to your situation instead of assuming, making the search fit a schedule built around shifts, nights, and call rather than a nine-to-five routine, and planning the timing around contract dates and start dates. No occupation automatically unlocks a loan, grant, or discount, and this guide makes no assumptions about your income, household, or eligibility. Get the written pre-approval, verify every product with the lender or agency that offers it, build the shortlist from evidence, and let the written agreements carry the promises.
Key takeaways
- A written pre-approval comes before any touring; it sets the real budget and shows sellers you can act.
- Physician and doctor loans exist at some lenders, but eligibility, rates, and terms vary by lender, and none is a Rewarding Heroes benefit.
- Clinical schedules should shape the search: drive the commute at your real hours, place the neighborhood at the hours you sleep, and tour when you can actually be there.
- Contract and start dates set the buying timetable: orientation, credentialing, and moving windows all matter to a closing date.
- Rewarding Heroes is a consumer-first service program with a clearly stated fee structure, not a cash-back arrangement and not a special price on every home.
What is the Rewarding Heroes program, honestly?
Rewarding Heroes is the program Andrew Texidor founded within Clearly Sold for military, first responders, law enforcement, fire and rescue, teachers and school administration, doctors, nurses and healthcare professionals, Border Patrol, and utility workers. It is brokered by HomeSmart. Its mission is to bring the same consumer-first clarity this site is built on to the people who serve the community: a clearly stated fee structure, a defined scope of work, and an agent who answers questions plainly. It is a real estate service program, not a cash-back or rebate arrangement, and not a promise of savings.
The standard structure is $8,000 per applicable transaction side for sale prices up to and including $550,000, and 2% of the full sale price above $550,000. Fees and services are governed by the applicable written agreement, and buyer-broker compensation is separate and negotiable. Any feature, pricing detail, or eligibility point of the program is confirmed in the written agreements for your transaction, and those agreements are the only promises that count.
You will meet other brands and programs with similar-sounding names, and no affiliation with any of them is claimed here. Ask every provider, in writing, who they are, what they include, and what they cost, and hold them to the same standard.
The buying process, step by step
Set the budget with a written pre-approval
Begin with lenders, not listings. A pre-approval letter states the amount a lender is willing to underwrite today, the cash needed to close, and an estimated monthly payment. Compare two or three lenders and ask how clinical income is documented: salaried hospital wages, overtime or per-diem patterns, contract or 1099 work, a residency or fellowship match letter, or a signed employment contract as a new attending each get treated differently depending on the lender. Get every answer in writing.
Sort the financing options without assuming anything
Physician and doctor loan products exist at some lenders for medical and dental professionals, and this article describes them because they come up often, not because any reader qualifies. Features commonly include a lower down payment or none, no private mortgage insurance, and student loan treatment that differs from a standard review, but each lender sets its own eligibility, rates, and terms, and many of these products carry modestly higher rates or adjustable-rate periods. Compare them against FHA and conventional financing, and against VA loans for those who earned VA eligibility through qualifying service. Every product is verified with the lender that offers it, and none of them is a Rewarding Heroes benefit.
Choose the search area on evidence
Build a shortlist from commute time at the hours you actually drive, proximity to the medical center or campus where you work, how the neighborhood sounds at the hours you sleep if you work nights, community fees, and lifestyle fit. Drive the routes at your real shift times. If a specific community is on the list, verify HOA fees and rules before you fall for the home.
Tour with purpose around your schedule
When 12-hour shifts and call leave little slack, use the tools that fit the gaps: tour before or after a shift, stack showings on a single day off, and use video walkthroughs for homes you cannot visit in person. Compare every home on the same assumptions: condition, monthly fees, tax and insurance estimates, and what each needs in work and money.
Offer with terms, inspect with discipline
An offer pairs price with terms: earnest money, closing date, and contingencies. In Arizona a due diligence window covers inspections and the Seller's Property Disclosure Statement. Spend that window properly, even when your schedule is thin: inspections, documents, and the community's fee picture can all be reviewed with a local team while you work.
Close with the checklist done
Confirm the final numbers with the title company and lender, keep deposit and closing funds ready, and make sure the move and first-payment dates line up with your start date and orientation schedule. Arizona closings are often done remotely and on flexible schedules, but confirm signature and notary requirements with the title company early, and get everything in writing before the closing date.
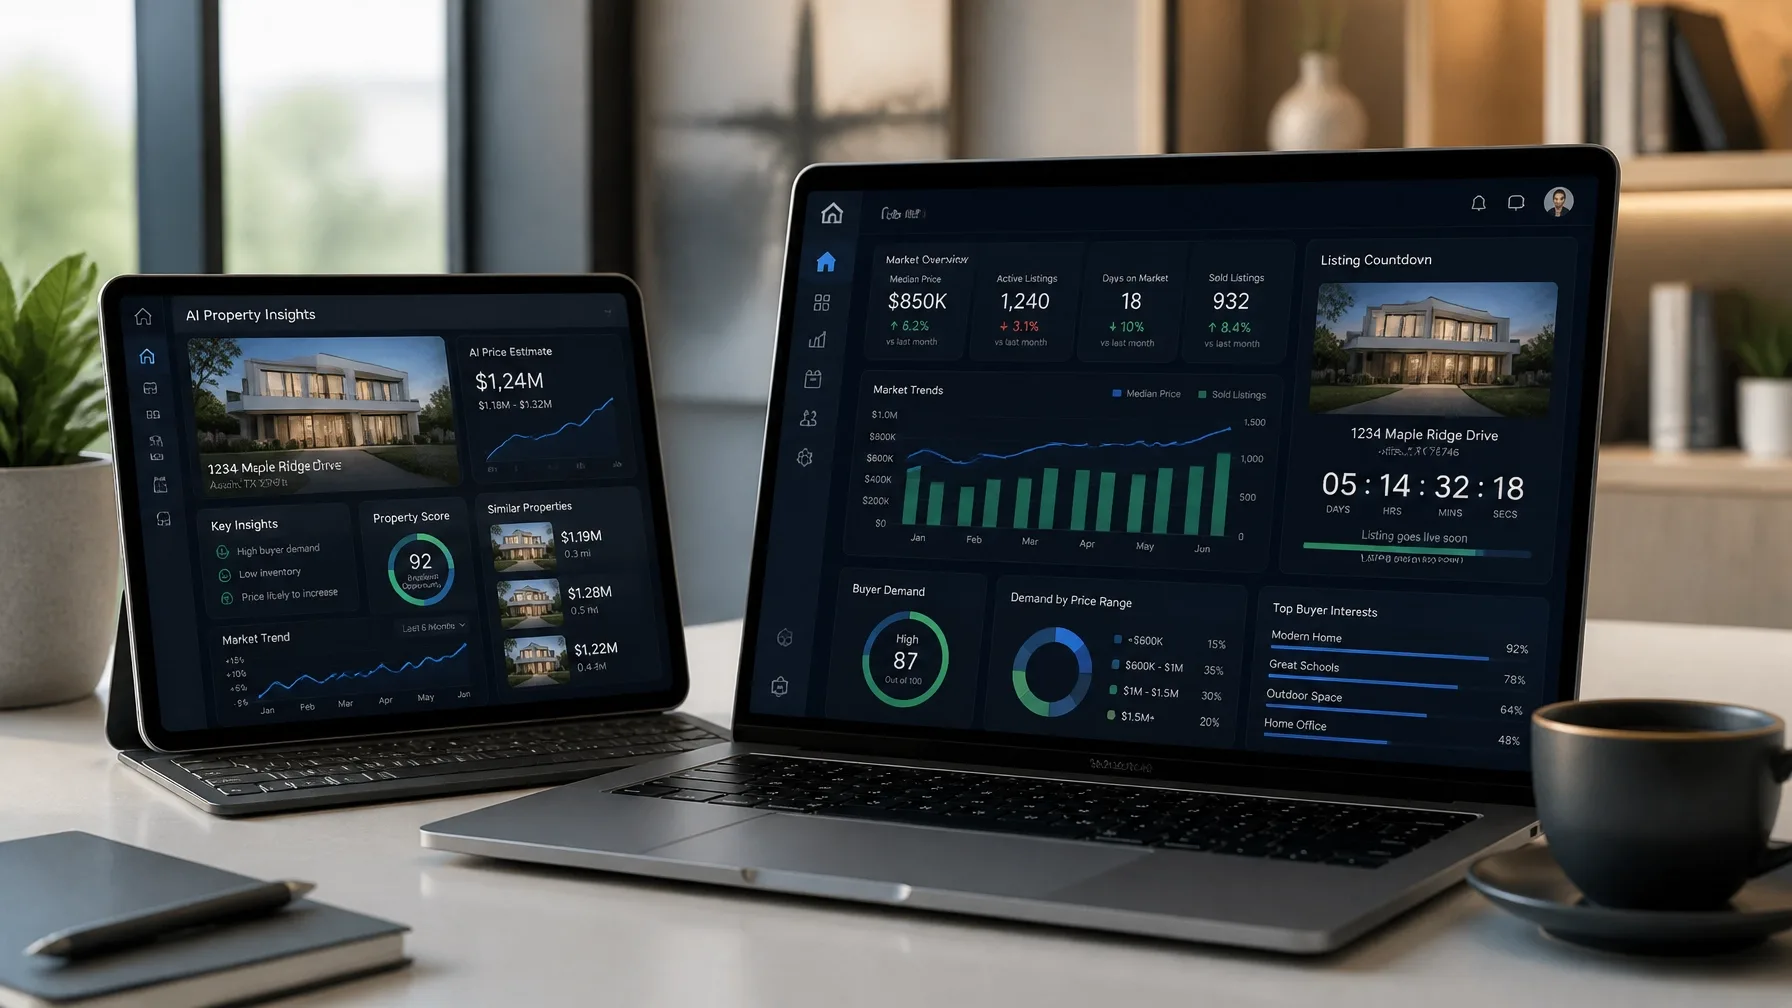
Which financing is actually worth verifying?
The first thing to clear away is the assumption that any occupation unlocks financing. Physician and doctor loan products exist at some lenders and are designed for medical and dental professionals whose early-career savings may lag their income: residents and fellows, new attendings, and established physicians and dentists. Common features include a lower down payment or none, no private mortgage insurance, and student loan obligations treated differently in underwriting. The tradeoffs are just as real: these are conventional products from private lenders, rates can run modestly higher than a conventional loan for the same borrower, some are adjustable-rate, and credit and documentation minimums vary by lender.
Eligibility also varies. Many lenders cover MDs and DOs, dentists, and other advanced-degree healthcare roles, and some include nurse practitioners, physician assistants, and other clinical professionals, but the exact list is the lender's own decision, so it must be verified with the lender, not assumed. Compare these products against FHA and conventional financing, and against VA loans for anyone who earned VA eligibility through qualifying service. Down payment assistance programs in Arizona cities and counties have their own income caps, price limits, and deadlines that change year to year.
For every financing route, ask the same four questions: do I meet the current eligibility rules, what exactly is included, what is the rate and how long does it hold, and what happens if a rule changes before closing? Get the answers in writing from the lender or agency, not from a forum or a flyer.
How should clinical schedules shape the search?
More than most buyers expect. A commute experienced at 5 a.m. before a 12-hour shift is different from the one on a map at noon, and a neighborhood that seems quiet during a Saturday tour may be something else at 2 a.m. when you are trying to sleep after a night shift. Drive the routes at the start times of your shifts, visit the community at the hours you will actually be home, and think through parking and garage space, secure storage for gear, and whether overnight street parking works where you are looking. An HOA's rules on vehicles, trailers, and rentals are worth a direct question, because they vary by community and can change what a home really supports.
None of this is about labels or steering for who belongs in a neighborhood. It is about matching the objective housing, access, and lifestyle facts to your specific routine, which every buyer should do on their own evidence.
How do you coordinate a purchase with a contract or start date?
The calendar of a clinical job change usually starts with a signed contract, then orientation, credentialing, and a start date, and each step can slip. The practical approach is to build a time buffer: confirm how much lead time your employer needs for credentialing and orientation, aim to close and move before the date you report, and keep the sale or lease of your current home on a parallel but flexible track. If you are selling and buying at the same time, the sequence matters: sell first, buy first, or overlap with a contingency are all real options with different tradeoffs.
If your employer offers a relocation benefit, treat it as part of the financial picture, not as a promise that changes the transaction: verify the amount, the repayment conditions, and the tax treatment with your HR office and your tax professional, because those details vary by employer and by situation.
Where do healthcare careers in the West Valley actually work?
The West Valley's medical geography is spread out, which is exactly why the commute answer depends on where you work, not on the general area. Full-service hospitals and medical centers in and around the corridor include Banner Estrella Medical Center in west Phoenix, Abrazo West Campus in Goodyear, Banner Del E. Webb Medical Center in Sun City West, Banner Boswell Medical Center in Sun City, Banner Thunderbird Medical Center and Abrazo Arrowhead Campus in Glendale, and Abrazo Surprise Hospital near Loop 303 and Bell Road in Surprise. Banner has also announced a hospital project in Buckeye, still reported as announced rather than open: the Banner article covers the details .
These are examples of where healthcare work happens in the corridor, useful as a starting map, not as an assumption about anyone's assignment. Clinics, surgery centers, urgent care, and outpatient campuses open and change locations, and your workplace may be none of these. The test that matters is yours: drive the route from a candidate home to your actual workplace at the time you actually travel.
What can technology do for a time-constrained search?
Andrew is an AI Certified Agent™, and the tools behind Clearly Sold exist to put the options, costs, and tradeoffs in front of you in a form you can act on between shifts. For healthcare professionals specifically, the Rewarding Heroes program page describes AI-driven home shopping tools that help organize the search and narrow the options around demanding schedules. In practice that means saved searches and listing alerts that run while you work, side-by-side comparisons that keep every home on the same cost and condition assumptions, and video walkthroughs that stand in for a visit you cannot make in person.
The honest limit is the same one this site applies everywhere: tools organize information and make the tradeoffs visible, and they never replace professional judgment, never promise outcomes, and never guarantee a price, a timeline, or an approval. The decisions are yours, made on evidence you can see. If you want to know what a tool does with your own numbers, ask, and we will show you rather than tell you.
What should you verify, and with whom?
Verify with your lender
Program eligibility, how clinical income is documented, rate locks, and how long approvals hold. Compare two or three lenders and get estimates in writing.
Verify with your employer
Contract terms, start and credentialing dates, and any relocation benefit, including repayment conditions and tax treatment. Ask HR directly, and get it in writing.
Verify the community
HOA fees and rules on vehicles, rentals, and parking, plus current property taxes and insurance estimates, address by address and street by street.
Frequently asked questions
What is Rewarding Heroes, and is it a discount for healthcare workers?
Rewarding Heroes is a real estate service program founded by Andrew Texidor within Clearly Sold and brokered by HomeSmart, built for military, first responders, teachers, healthcare professionals, and public servants. It is a consumer-first service program with a clearly stated fee structure, not a cash-back or rebate arrangement, and not a discount on every home. The standard structure is $8,000 per applicable transaction side for sale prices up to and including $550,000, and 2% of the full sale price above $550,000, with fees and services governed by the applicable written agreement and buyer-broker compensation separate and negotiable. Any feature or pricing detail is confirmed in the written agreements for your transaction.
Are physician or doctor loans part of Rewarding Heroes?
No. Physician and doctor loans are mortgage products offered by individual lenders to medical and dental professionals, with eligibility, rates, and terms that vary by lender. Rewarding Heroes is a real estate service program, not a lender, and it offers no loan products of its own. You can use a doctor loan and a service program together, but each is verified on its own: loan terms with the lender that offers them, and program terms in the written agreement. No affiliation between any lender and Rewarding Heroes is implied.
Do doctors and nurses automatically qualify for special financing?
No occupation automatically qualifies anyone for a loan, grant, or discount. Physician loan eligibility is set by each lender and commonly covers MDs and DOs, dentists, and often other advanced-degree healthcare roles, but the exact list varies by lender and the terms vary by borrower. Down payment assistance programs have their own income caps, price limits, and deadlines that change year to year. Verify current eligibility and terms with each lender or program, never from memory or a headline.
How should I verify my income if I am a resident, fellow, new attending, or travel nurse?
Lenders document income according to how it is paid and how long the history is: W-2 wages from a hospital employer, overtime or per-diem patterns, contract or 1099 work, a residency or fellowship match letter, or a signed contract as a new attending all come with different documentation expectations. Some lenders will consider a match letter or employment contract with no prior income history, and each lender sets its own rules for the two-year histories that self-employment and contract income typically require. Ask your lender directly how your exact situation is documented, and get the answer in writing.
Can I buy a Phoenix-area home before my start date or from out of state?
Usually yes, with the right structure. Buying ahead of a start date works when the contract and closing timeline line up with your orientation, and remote buying works when a local team handles what you cannot: inspections, appraisals, video walkthroughs, and the closing, which Arizona title companies can conduct with remote identity verification. Confirm documentation, signature, and notary requirements with your lender and title company early, and be honest about the judgment calls you are deferring to video and to your agent.
Related resources
- Rewarding Heroes for healthcare workers The program page for doctors, nurses, and other healthcare professionals at local medical centers and hubs.
- Rewarding Heroes program A real estate service program founded by Andrew Texidor and brokered by HomeSmart, with the fee structure in writing.
- Home buying process The step-by-step path to an Arizona purchase, from pre-approval to keys.
- Down payment and grant programs An honest look at programs that may help, and what to verify with each provider.
- VA loans, conventional loans, and hero programs How mortgage products and service benefits play different roles, with eligibility to verify independently.
- Sell first or buy first? How to coordinate a sale and a purchase around one move, with the tradeoffs of each sequence.
- Banner Health expansion in the West Valley What Banner has announced: the Buckeye hospital plan and the Goodyear health center, reported as announced.
- Book a strategy call Walk through your situation, the fee structure, and the first steps on your own numbers.
Sources and verification: physician and doctor loan features and tradeoffs as generally described by lender and financial-education sources (White Coat Investor, Truist, and others), with each lender's own terms as the authority. Medical center locations as listed by the facilities and regional health-system pages, with the Banner Buckeye hospital project reported as announced. This article explains how the Arizona home buying process generally works, with context for healthcare professionals. It is not legal, tax, lending, employment, relocation-benefit, or financial-planning advice, and it makes no claim about any program's current terms. Loan products, assistance funds, benefits, rates, fees, and taxes change and vary by provider, employer, agency, county, and transaction. Verify current eligibility and terms with your lender, your employer, the program's own office, and your tax professional before you commit.
Next step
A clear buying plan, built around your schedule
A short call maps the process to your clinical calendar: which financing to verify, what the commute evidence says, and the first steps this month. No assumptions, no cash-back hype, just the plan.
- Phone
- 623-400-5957
- hello@clearlysold.com